How much of your dividend income would you actually keep in Cyprus?
Work out the difference before you speak to anyone. The figure below is yours to check, not ours to claim.
Designed for internationally mobile founders and business owners considering a genuine move to Cyprus.
Two inputs
No email address required. Change the figures and see the result immediately.
2026 rate presets
UK uses the 2026/27 dividend bands and personal allowance taper at £0.87 per €1, so the rate moves with your income. Other countries show headline 2026 rates. If you know your own rate, use the slider.
Where you are now
€220,050
Indicative personal tax on the dividend income above using the rate selected.
Cyprus, as a Non-Dom
€4,770
Estimated GHS contribution at its annual ceiling. No SDC on dividends for a qualifying Non-Dom.
Potential annual difference
€215,280Question 1 of 4
Does this figure hold up for you? Start here.
Which best describes your situation?
How this is calculated
This illustration compares personal tax on dividend income only. It does not calculate company-level tax before profits are distributed. The country presets are indicative 2026 headline or default rates and are provided only as starting points. They do not calculate the visitor's actual effective tax liability and do not account for income bands, allowances, exemptions, progressive taxation, church tax, special shareholder rules, foreign tax credits, treaty relief, source-country withholding or other individual circumstances. For Cyprus, the illustration assumes the individual qualifies as both a Cyprus tax resident and Non-Dom. A qualifying Non-Dom is generally exempt from Special Defence Contribution on dividends. General Health System contributions apply at 2.65%, subject to a maximum annual contribution base of €180,000. The calculation assumes that this €180,000 GHS contribution base has not already been used by other GHS-contributable income. If it has, the additional GHS attributable to the dividends may be lower. This calculator is an illustration only and is not tax advice.
Want the rules behind the calculation? Read the full Cyprus Non-Dom guide .
Your circumstances
The calculation is simple. Your actual position is not.
Answer four short questions about your situation and income in Cyprus. We will tell you whether Cyprus is worth exploring further and whether Royal Pine is the right firm for your situation.
Apply for a strategy call Not every enquiry is a fit. We will say so if it is not.What happens next
Tell us where you are now
Your situation, your expected income in Cyprus and whether a move is genuinely under consideration.
We assess the fit
We look at whether Cyprus and the Non-Dom regime are relevant before asking you to spend time on a call.
Speak when there is something to discuss
If there is a credible case, the next conversation can focus on your actual structure rather than generic Cyprus information.
Where this works
- You own the business rather than run someone else's, and you decide how profits are taken.
- A meaningful proportion of your personal income comes from dividends, interest or investment returns rather than salary.
- You are willing to relocate properly and establish genuine Cyprus tax residence.
- You are planning ahead rather than trying to restructure after a transaction has already completed.
Where it does not
- You want the Cyprus tax position without genuinely relocating. Cyprus tax residence requires the relevant conditions to be met.
- Your income is mainly employment salary. Non-Dom status itself does not exempt salary from Cyprus income tax.
- You have already been a Cyprus tax resident for 17 of the previous 20 years. The standard Non-Dom exemption period has ended, although qualifying individuals may have further options under the current regime.
- You are already at the point of signing or completing a transaction. Residence, structuring and departure-country consequences are much harder to address retrospectively.
If the fit is not there, knowing that early is useful too.
What this can look like in practice
Software company, relocated with spouse and two children
Anonymised from a recent engagement. Figures illustrative.
Licensing and software operations moved to a Cyprus trading entity serving international clients. Qualifying IP income was structured through the IP Box regime, with Non-Dom status layered on top for the personal side. Total effective tax leakage of roughly 12%. Family permanently relocated.
UK entrepreneur, business valued above £30M
Anonymised from a recent engagement. Figures illustrative.
He relocated to Cyprus ahead of the sale and established Cyprus tax residence before completing the transaction. He is now redeploying proceeds into Cyprus property and international securities. In his circumstances, no Cyprus capital gains tax arose on the share sale. Departure-country consequences were assessed separately.
Who assesses your case
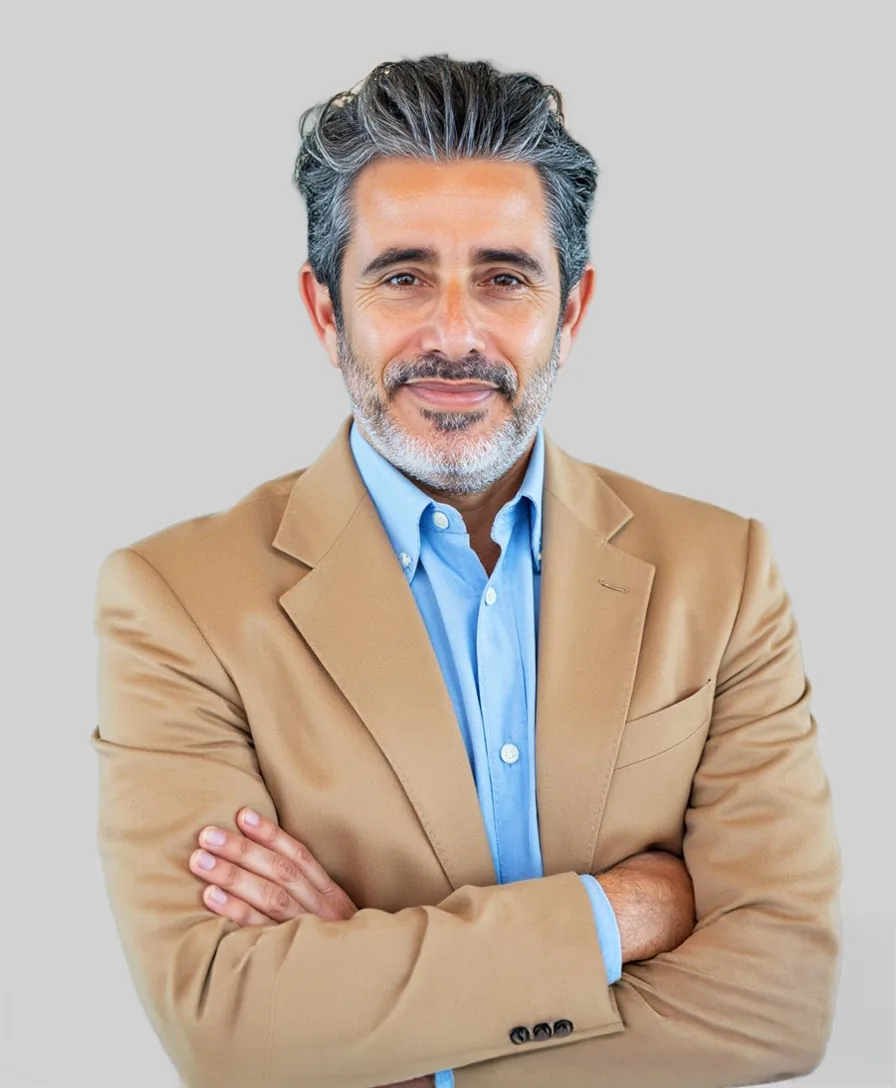
Constantinos Economides
Founder and Managing Director of Royal Pine. Twenty years in the industry, including Ernst & Young in London and Deloitte in Cyprus, before establishing Royal Pine in 2016. Royal Pine is regulated by ICPAC, the Institute of Certified Public Accountants of Cyprus.
The next step
Find out whether the number holds up in your case
Four short questions. A clear answer on whether Cyprus fits you.
Apply for a strategy call